Taxpayer Journey Flowcharts
Complexity compared
The diagrams below map two systems: the WDT taxpayer journey and the current UK tax system. They are shown side by side so the structural comparison is immediate rather than something the reader has to reconstruct from memory.
The UK system’s complexity is a historical artifact — Income Tax, NICs, CGT, IHT, Corporation Tax, VAT, and SDLT each evolved separately, governed by different logics, on different schedules, with different definitions of the same underlying concepts. Nobody designed it as a whole.
The WDT is also complex. But its complexity is the complexity of a complete system: every branch has a reason, and the reasons connect. The valuation routes exist because assets differ in liquidity. The privacy election exists because disclosure has social costs that the rate schedule should price. The lifetime envelope exists because refunds must be bounded to prevent gaming. Dense flowcharts do not, by themselves, indicate poor design.
| Metric | WDT | Current UK system |
|---|---|---|
| Nodes (full chart) | 68 | 107 |
| Decision points | 18 | 37 |
| Edges | 78 | 140 |
| Distinct tax regimes | 1 | 12 |
Click any diagram to expand it. Right-click → Open Image in New Tab for the full-resolution version.
Overview: ten steps vs a year of taxes
Start here. The skeletons strip each system to its spine — enough to understand the shape before the detail becomes legible.
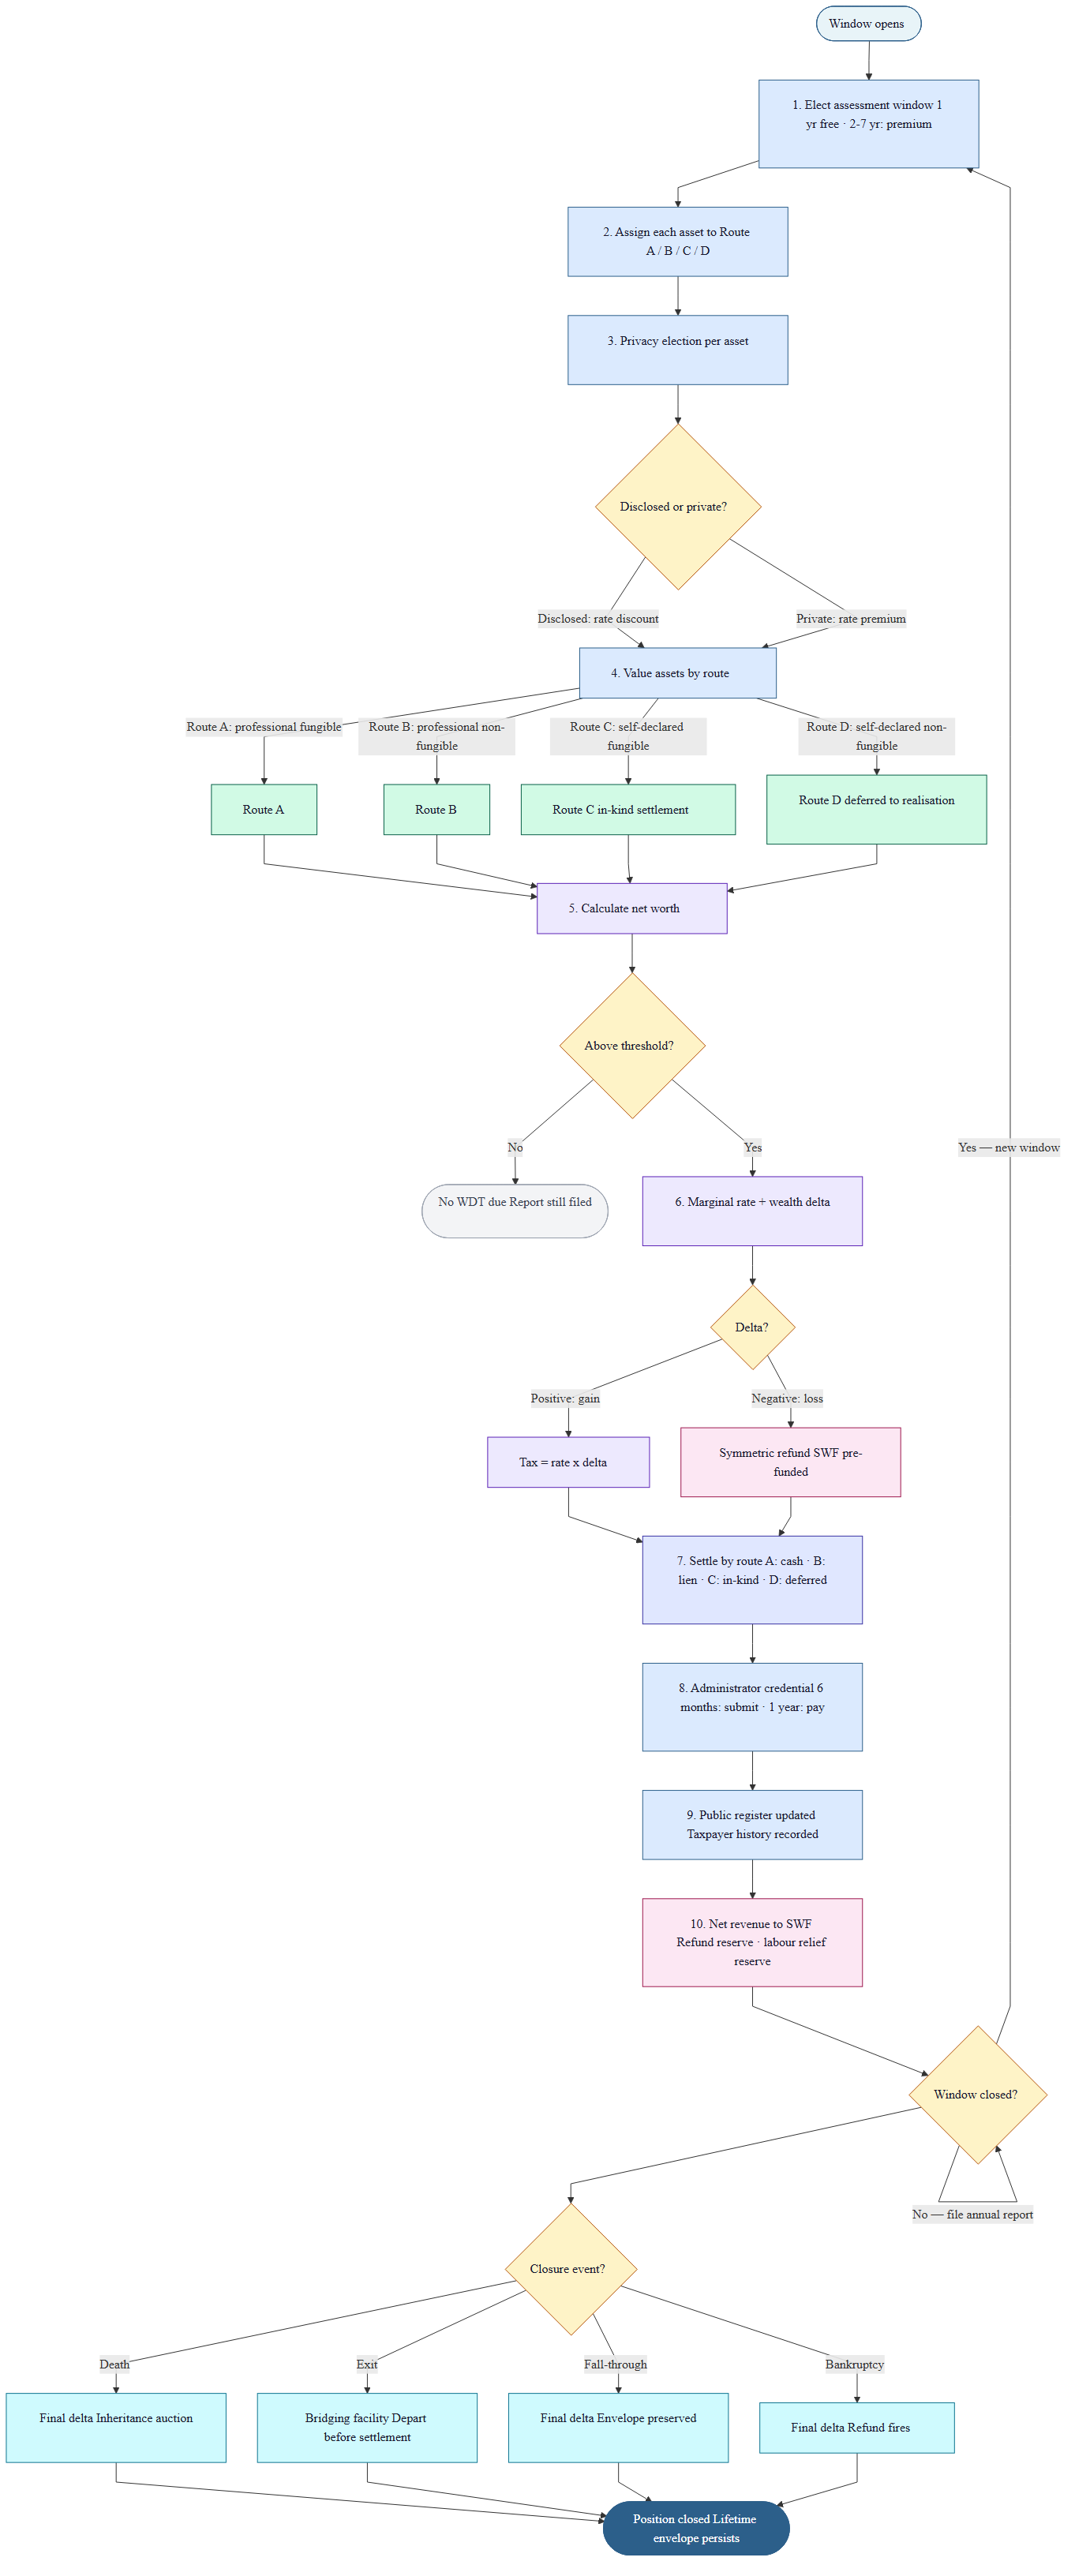
WDT overview — 28 nodes
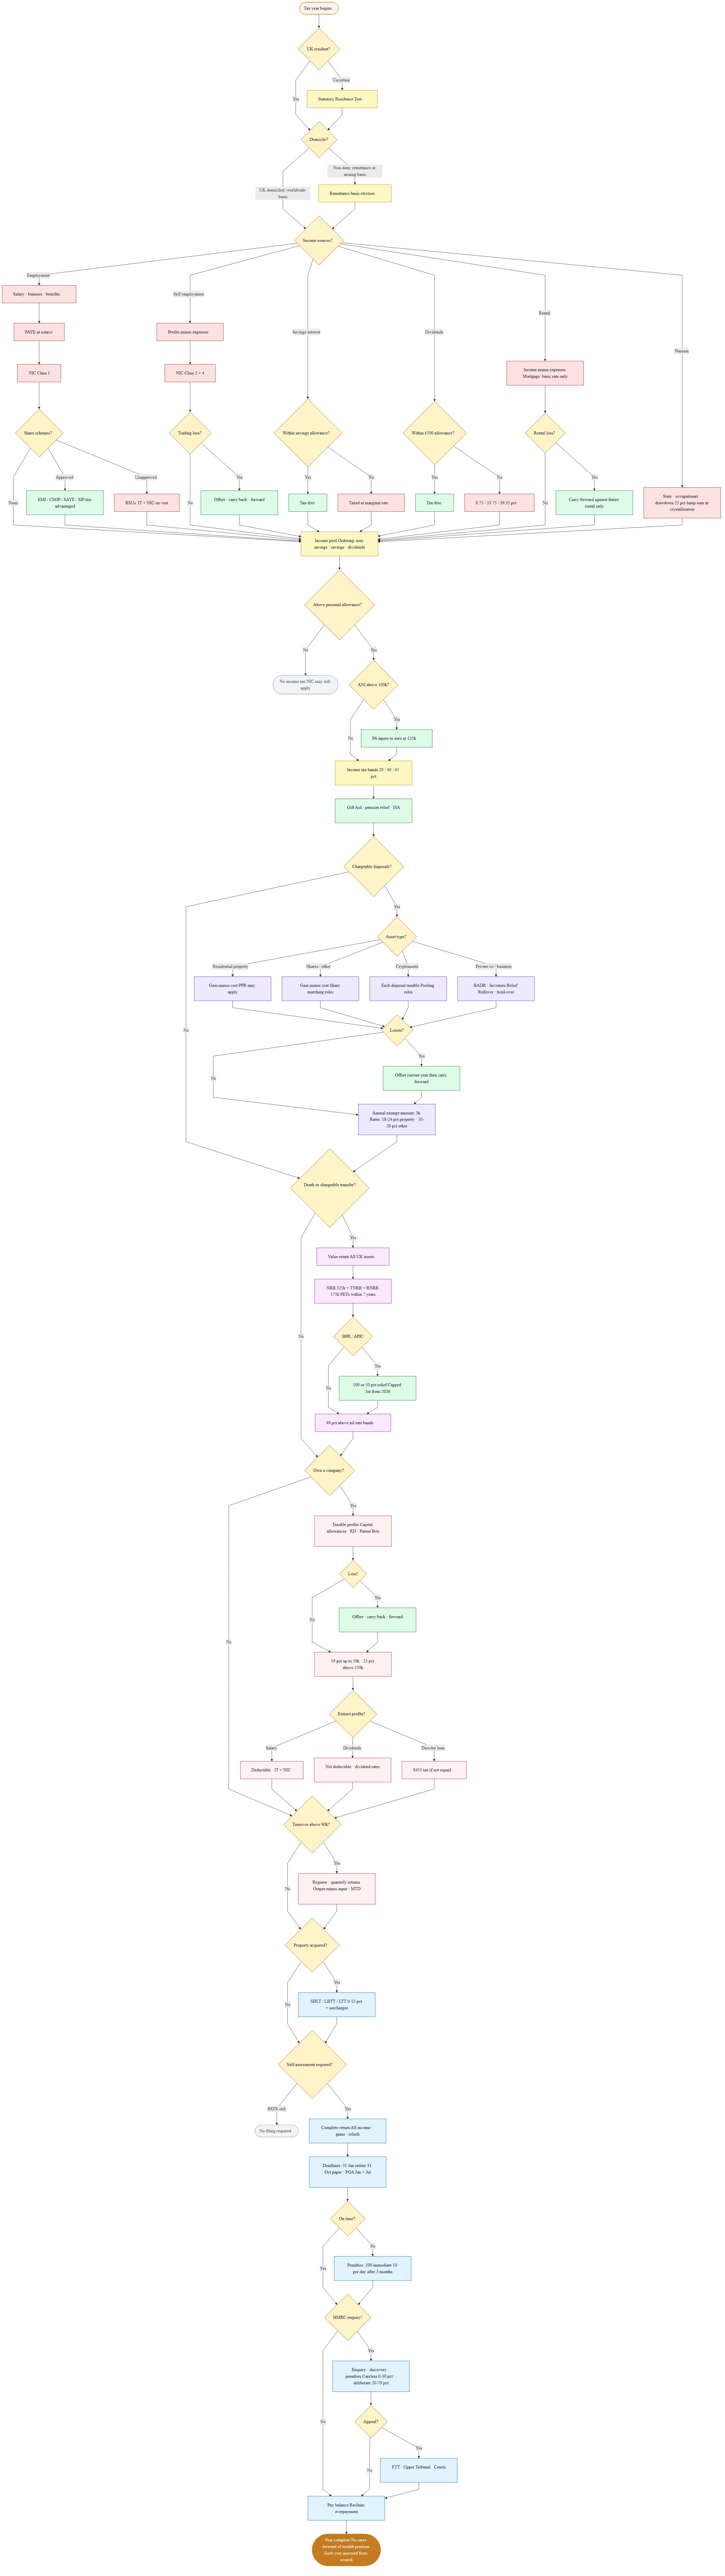
UK system overview — 73 nodes
The WDT skeleton traces a single continuous journey: open a window, assign routes, value assets, calculate the delta, settle, loop. The UK skeleton branches immediately into parallel income streams — employment, self-employment, savings, dividends, rental, pension — each with its own loss rules, reliefs, and deadlines, before they converge in the income pool and then fan out again through CGT, IHT, Corporation Tax, VAT, and SDLT.
Full detail
The full charts add every decision branch: valuation disputes, route-specific settlement mechanics, the corporate levy credit system, the Route D auction trigger, and all four closure events on the WDT side; share schemes, remittance basis, pension annual allowance tapering, all CGT asset classes, the BPR/APR cap, three VAT schemes, three SDLT jurisdictions, and the full HMRC enquiry and penalty ladder on the UK side.
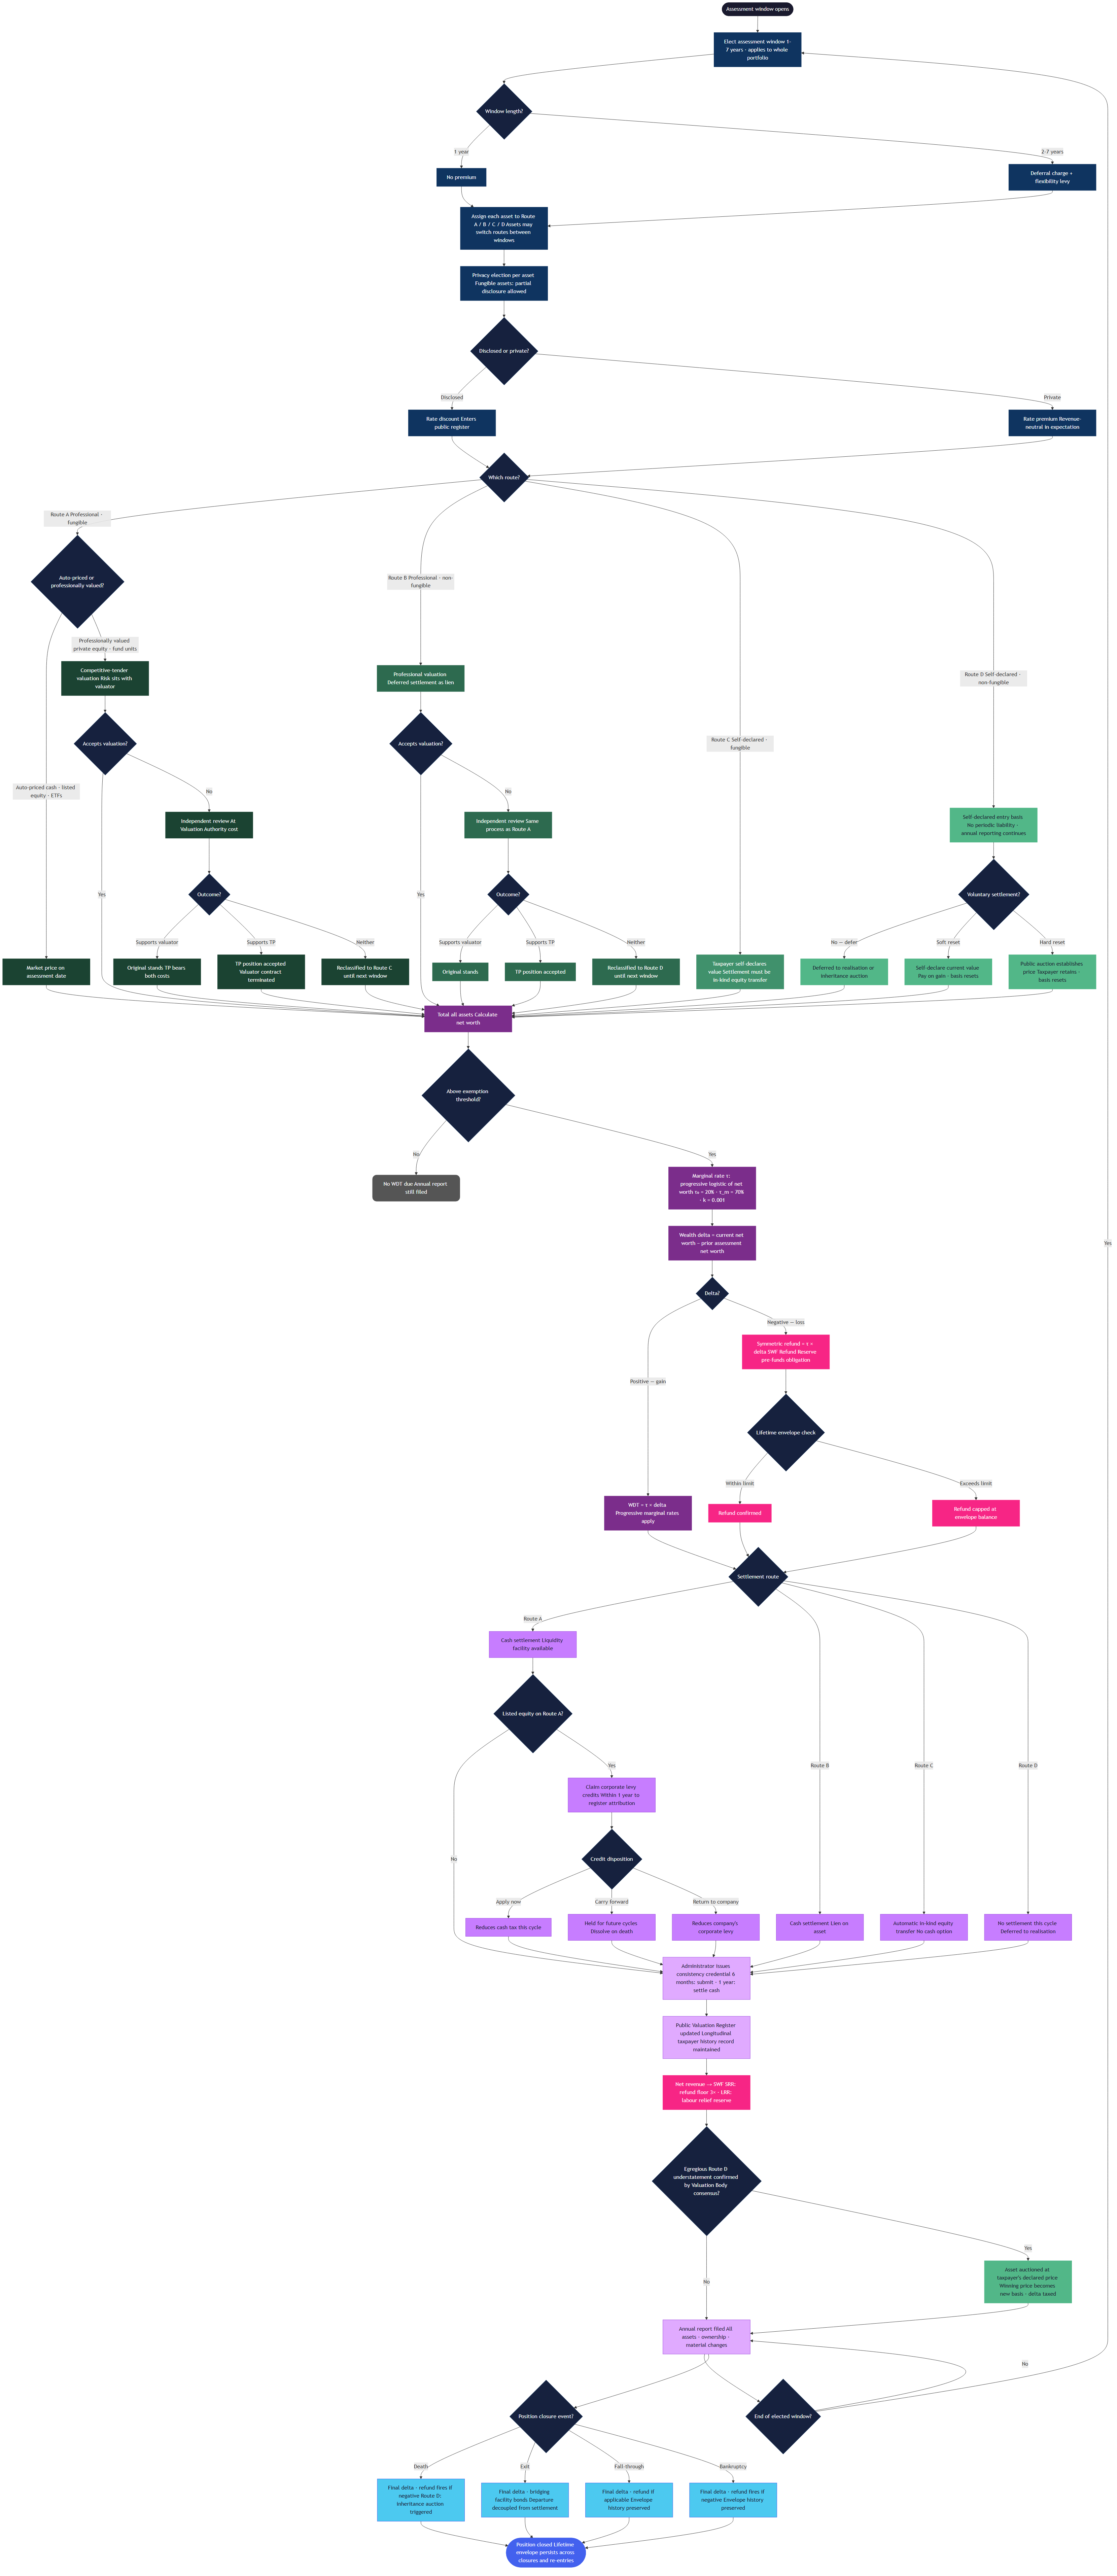
WDT full detail — 68 nodes · 18 decisions · 78 edges · 1 tax
UK system full detail — 107 nodes · 37 decisions · 140 edges · 12 tax regimes
The core mechanic
Before either flowchart is relevant, the underlying logic is this: the state shares in wealth movement symmetrically, in both directions, through a public fund that pre-finances the refund obligation.
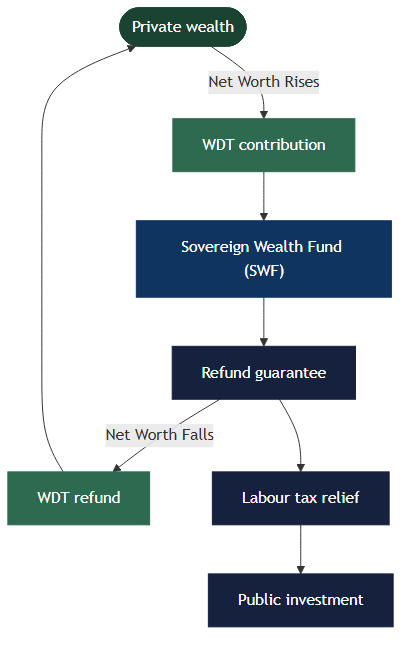
WDT bidirectional flow — private wealth ↔ public wealth fund